Compounding occurs when a return is earned not only on the original amount invested but also on earlier returns that remain invested. It is a mathematical process, not a special product and not a guarantee. Its effect depends on time, contributions, actual returns, costs, taxes, and whether gains remain invested.
The basic mechanism
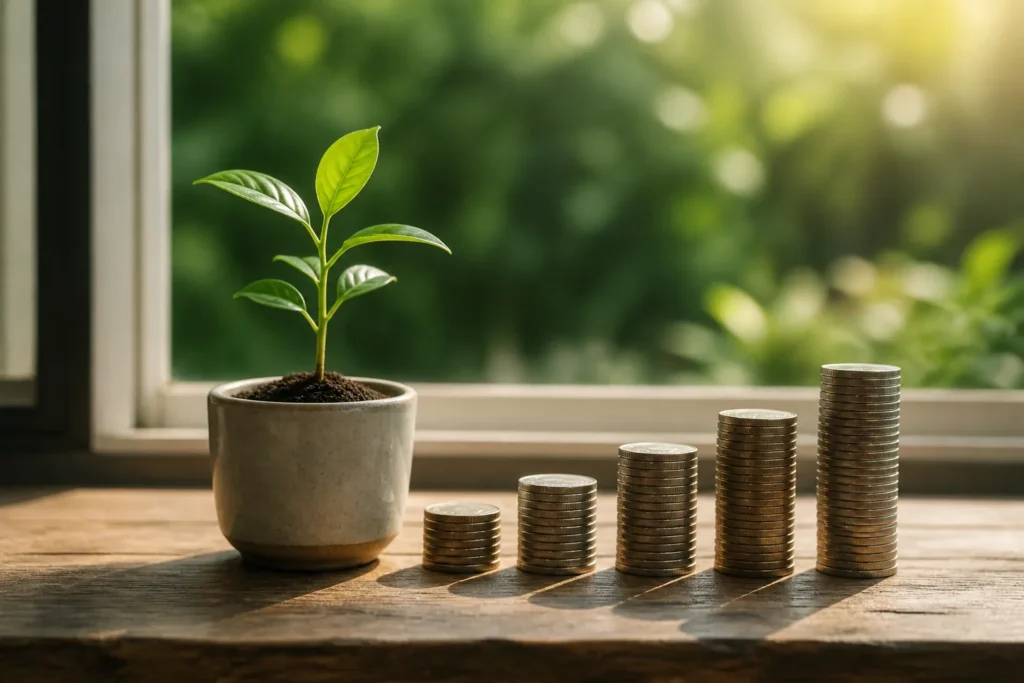
Suppose an amount grows during one period. If the full balance stays invested, the next period begins with a larger base. A positive return on that larger base includes a return on earlier gains. Repeating that cycle can make growth accelerate over long periods.
The same mathematics can work in the opposite direction. Losses reduce the base available to recover, fees reduce the amount left to compound, and withdrawals interrupt the process. A smooth calculator curve should therefore be read as an illustration, not a forecast of how markets will behave.
Why time matters
More time means more potential compounding periods. Starting earlier may reduce the contribution required to pursue a long-term goal, but an early start does not make an unsuitable investment safe. Every investment can lose value, and the correct risk level still depends on the goal, time horizon, liquidity needs, and capacity for loss.
Starting later is not a reason to chase a higher return. The more controllable responses are to revisit the target, increase sustainable contributions, adjust the time horizon, reduce costs, or combine those changes.
Contributions are part of the result
Regular additions can matter as much as the assumed return. Separate the balance into three parts when reviewing a projection: money contributed, estimated growth, and total value. This prevents investment gains from being confused with money that came from your own deposits.
Automating contributions can make a plan easier to repeat. It does not remove market risk, guarantee a profit, or determine whether the selected investment is appropriate.
Small differences in assumptions become large
A long projection is highly sensitive to the return assumption. Compare several plausible scenarios instead of relying on one optimistic number. Include a lower-return case, a central case, and a stress case. If the plan fails after a modest change in return, contribution, or time horizon, the plan may not have enough margin.
Costs deserve the same treatment. Fund expenses, advice fees, trading costs, account charges, and taxes can reduce the balance that remains invested. The SEC notes that even small fee differences can translate into meaningful differences in results over time.
A disciplined way to use a compounding calculator
Enter what you already have for the goal, then choose a contribution that fits the household budget and a period that matches the real target date. Run several return assumptions, including a difficult case. Check whether the result is nominal or adjusted for inflation, and account separately for fees and relevant taxes. Revisit the calculation when income, costs, or the goal change materially.
Compounding is most useful as a planning lens. It shows why time, consistency, and costs matter; it cannot tell an investor which return the future will deliver.
Break the ending value into understandable parts
A projection combines the starting balance, later contributions, investment returns, fees, taxes where applicable, and time. Separating those inputs prevents the chart from implying that all growth came from investment skill. For many early-stage plans, consistent contributions account for a large share of the ending balance.
A simple illustration shows the mechanism. If 100 earns 5% in one year, it becomes 105. If the next year’s 5% applies to the full 105, the balance becomes 110.25. The extra 0.25 is return earned on the earlier return. Real investments do not deliver a fixed annual rate, so the arithmetic explains compounding but not the path an investor will experience.
Sequence matters when cash enters or leaves
Two portfolios can report the same average annual return and finish with different outcomes if gains and losses arrive in a different order while contributions or withdrawals are occurring. Early declines may allow recurring contributions to buy at lower prices, but declines near a planned withdrawal can be damaging because money leaves before a recovery.
This is why a retirement projection should include contribution timing, withdrawals, and adverse scenarios. A single smooth growth line hides the uncertainty that matters most to the plan.
Test the assumptions, not just the headline result
Try lower and higher returns rather than one expected rate. Include fees and, where relevant, inflation. See what changes if contributions pause, the starting date slips, or a material drawdown arrives early rather than late. Keep the nominal ending balance distinct from its purchasing power.
Small annual fees also compound in the opposite direction. The charge reduces the balance today and removes the future growth that balance might have earned. Comparing net-of-fee scenarios is therefore more informative than looking only at the stated expense percentage.
Use the portfolio simulator to examine ranges and stress scenarios. Treat every result as conditional on the inputs. Compounding rewards time only when capital remains invested in a suitable, sufficiently diversified plan and the investor can tolerate the path.
A complete contribution example you can check
Suppose a hypothetical investor starts with $10,000 and adds $200 at the end of each month for ten years. Use a constant 5% annual return assumption, with fees, dividend yield and inflation all set to zero. This is a calculation exercise, not an expected return for any asset.
Over 120 months, the investor contributes $24,000 in addition to the original $10,000. Total money contributed is therefore $34,000. The monthly rate is 1.05 to the power of one twelfth, minus one. The simulator grows the existing balance at that rate, then adds the next $200 contribution. Its projected ending balance is approximately $47,161.58, including approximately $13,161.58 of modelled growth.
Begin with the filled contribution example. Compare the total contribution figure with your own calculation before looking at the growth figure. This is a useful check that the duration and deposit frequency are correct.
Change the monthly contribution to $100 while keeping the other inputs fixed. Then restore $200 and lower the annual return assumption to 3%. These are different experiments: the first changes a planned cash flow, while the second changes an uncertain market assumption. Neither test establishes what you personally should invest.
Finally, select a stress scenario and compare the result with the normal scenario. The historical presets simplify selected market declines rather than replaying a complete historical portfolio. They help expose sensitivity to adverse returns, but they do not tell you the probability of reaching either balance.
When recording the result, retain the starting balance, monthly amount, duration, assumed return, costs and scenario. An ending number without those inputs is not a useful plan. If you want to compare purchasing power, add inflation and read the inflation adjusted output alongside the nominal balance.
See how returns, contributions, costs, inflation, and time interact without mistaking a smooth projection for a promise.
Key assumptions
- The cited evidence remains representative and no material contradictory information has emerged.
What could invalidate the view
- New filings, policy decisions, market data, or methodology changes could alter the interpretation.
- Editorial ownership
- Market Master · reviewed
- Approval state
- Reviewed financial content
- Evidence currency
- Current evidence window
- Source coverage
- 6 documented sources
Editorial responsibility
Owner-operated and evidence-led
Market Master is an independent, owner-operated publication led by Andrejus S. Articles are published only after a recorded human review of their claims, sources, calculations, and wording. Sources and review status appear in the evidence ledger.